
Business travel spend: what employees can claim and how much
Published: Oct 5th, 2026
Key takeaways:
- Employees can generally claim transportation, lodging, meals, and reasonable incidentals with a clear business purpose and documentation.
- There is no federal spending cap on business travel. The GSA's standard per diem of $178 a day is the most common benchmark.
- Per diem is tax-free to employees only when it stays at or below the federal rate and the trip qualifies as temporary business travel.
- The IRS meal and incidental (M&IE) rate splits into fixed shares: 15% breakfast, 25% lunch, 40% dinner, and 20% incidentals.
- A written policy needs six things: eligible categories, dollar caps, a documentation threshold, an approval workflow, a reimbursement timeline, and state-specific reimbursement requirements.
- Reimbursements stay off an employee's W-2 only under an IRS accountable plan, which requires a business connection, timely substantiation, and return of excess funds.
- The IRS raised the standard business mileage rate to 76 cents per mile effective July 1, 2026, up from 72.5 cents earlier in the year.
- A documented policy keeps business travel spend predictable for finance and simple for employees to follow.
Every business traveler eventually asks the same question on the flight home: what can I put on this expense report? For finance and HR teams, the tougher question is how much. Without clear rules, companies either overpay on vague allowances or underpay and annoy their most frequent flyers.
This blog breaks down business travel spend into what expenses employees can claim on a trip, how daily allowances work under current GSA and IRS guidance, and how to calculate a fair meal allowance. It also covers how a documented, benchmarked travel expense policy protects your budget, keeps reimbursements tax-free for employees, and cuts down the back-and-forth between travelers and accounting.
Whether you're building a policy from scratch or auditing an old one, use the rate tables and framework below as your starting point. Then see how Corporate Traveler's platform, Melon, automates the parts that used to take a spreadsheet and a strong cup of coffee.
What expenses can employees claim on a business trip?
Employees can generally claim transportation, lodging, meals, and necessary incidentals like baggage fees, parking, and Wi-Fi, provided the claim has a clear business purpose and documentation to back it up. Personal entertainment, family add-ons, and alcohol outside client entertaining are typically excluded.
All well-run travel policies sort claimable costs into the same six buckets: airfare or rail, ground transportation, personal vehicle mileage, lodging, meals, and incidentals. Nearly every company draws the line here. What separates a good policy from a mediocre one is the ceiling on each category and how strictly receipts get enforced.
Spell out each category, or spend the next year refereeing expense-report disputes. Ambiguity about what's excluded causes more friction than the reimbursable list itself ever will.
The table below lays out the standard categories most North American companies use, aligned to how the IRS treats each cost. Travel often? This is also where reducing airfare costs pays off twice: it lowers the fare itself, and a clear policy on baggage fees, seat selection, and other add-ons keeps that savings from disappearing into disputes over what's reimbursable.
| Category | Typical examples | Reimbursement basis | Tax treatment note |
| Airfare/rail | Coach fare, baggage fees, seat selection per policy | Actual cost with receipt | Fully deductible business expense |
| Ground transportation | Rideshare, taxi, rental car, parking, tolls | Actual cost with receipt | Fully deductible business expense |
| Personal vehicle mileage | Miles driven for business purposes | IRS standard mileage rate or actual cost | 76 cents/mile effective July 1, 2026, per IRS Announcement 2026-11 |
| Lodging | Hotel room rate and taxes | Actual cost, capped at GSA/company rate | Deductible; capped rate keeps reimbursement tax-free |
| Meals | Breakfast, lunch, dinner while traveling | Per diem (M&IE) or actual cost with receipt | Meals generally 50% deductible for the employer |
| Incidentals | Tips, baggage handling, business Wi-Fi | Per diem or actual cost | Covered inside the M&IE rate when using per diem |
For the full rundown of what qualifies as deductible for the business itself, IRS Publication 463 on travel, gift, and car expenses is the primary source worth bookmarking.
Stay in the loop.
The world of corporate travel is always changing. Sign up for newsletter and never miss a beat.
How much can employees spend on business travel?
There is no single legal spending cap on business travel. The ceiling is whatever your company policy sets. Most North American companies benchmark against the General Services Administrations’ (GSA) daily per diem, currently $178 in most US locations ($110 lodging, $68 meals and incidentals), and go higher in pricier cities.
Controlling business travel spend is a policy-design question, not a legal one, and companies solve it one of two ways: a fixed daily per diem that covers lodging and meals no matter what, or an actual-cost model with hard caps, like "hotel up to $250 a night in top-20 metros."
The GSA's federal per diem rates are the benchmark of choice for one simple reason: they're free, updated every year, and specific down to the county. For FY2026 (October 1, 2025 through September 30, 2026), the standard continental US rate sits at $178 a day, with roughly 300 higher-cost destinations charging their own premium.
Don't want to track hundreds of city-specific numbers? Use the IRS high-low method instead, a simplified two-tier system with one rate for high-cost localities and one for everywhere else. Either way, finance gets a defensible, IRS-aligned ceiling instead of a number pulled from thin air, and staying inside it gets a lot easier when travel policy compliance is built into the booking process instead of checked after the fact.
| Method | High-cost locality rate | Standard/other locality rate | Best for |
| GSA per diem (city-specific) | Varies by roughly 300 listed destinations | $178/day ($110 lodging + $68 M&IE) | Companies with concentrated travel to a few cities |
| IRS high-low method | $319/day ($233 lodging + $86 M&IE) | $225/day ($151 lodging + $74 M&IE) | Companies with travel spread across many cities |
Corporate Traveler works with SMEs across every stage of building a travel program, and this is usually the moment a client realizes the per-person rates set last year no longer reflect what a trip actually costs today. Our consultative approach means we sit down with your business specifically, not a generic template, to design a program around your actual goals and travel patterns.
What are the daily allowance rules for business travel?
A daily allowance pays a fixed rate for lodging and meals instead of reimbursing every receipt. It is tax-free to the employee when it does not exceed the federal rate and the trip qualifies as temporary business travel under an accountable plan.
Per diem exists for one reason: to simplify reimbursement without dragging it into taxable wages. Three conditions keep a per diem payment tax-free under IRS rules:
- The trip has a genuine business connection.
- The employee is temporarily away from their regular workplace.
- The daily rate doesn't exceed the federal rate.
Cross that line, and only the overage gets taxed. Skip the accounting altogether, and the whole payment turns into wages, no exceptions. First and last travel days get paid at 75% of the full rate, because nobody eats three full meals on a travel day.
Not a fan of per diem math? Reimburse actual costs with receipts instead. It sidesteps the formula but hands you more paperwork. Most mid-market and enterprise policies split the difference: per diem for meals and incidentals, actual cost with a cap for lodging and airfare. Layer in real-time visibility into airfare, hotel, car, and rail spend, and finance stops finding out at month-end.
-
1. Confirm the trip qualifies
The traveler must be away from their tax home overnight or long enough to require rest, and the purpose must be business-related.
-
2. Select a rate method
Choose either the GSA city-specific rate or the IRS high-low two-tier rate, and apply it consistently for the rest of the calendar year.
-
3. Apply the full daily rate on full travel days
Use the published lodging plus M&IE amount for every complete day away.
-
4. Apply 75% of the rate on travel days
Departure and return days are paid at three-quarters of the daily M&IE rate.
-
5. Deduct provided meals
If a conference or client provides a meal, subtract that meal's fixed percentage from the day's allowance.
-
6. Skip receipts for the per diem portion
Per diem, by design, does not require meal-by-meal receipts, only proof of the trip itself.
-
7. Document and pay within a reasonable window
Most companies mirror the IRS's 60-day substantiation guideline to stay inside an accountable plan.
What is a meal allowance and how is it calculated?
A meal allowance, the meals and incidental expenses (M&IE) portion of per diem, covers breakfast, lunch, dinner, and small incidentals like tips. The federal rate splits into fixed percentages per meal, so companies can prorate for partial travel days or provided meals.
Meal allowances get their own line item because meals are the part of a trip most likely to swing wildly and start arguments. The GSA and IRS solve this by publishing an M&IE rate and breaking it into standard meal percentages, so nobody has to invent their own math. For FY2026, the standard M&IE rate is $68 a day in most locations and $74 to $86 under the IRS high-low method, depending on the locality.
Break that total down: breakfast is 15%, lunch is 25%, dinner is 40%, and the last 20% covers incidentals like tips for hotel staff or baggage handlers. This matters most when a meal shows up free, say a working breakfast at a conference, because the company can cleanly deduct just that meal's share instead of eyeballing it.
It also matters on partial days. A same-day trip with no overnight typically doesn't qualify for any meal allowance under IRS rules, since there's no "away from home" requirement being met. Tie this to your broader travel budget, and forecasting gets a lot more predictable.
| Meal | Share of daily M&IE rate | Example at $68/day standard rate |
| Breakfast | 15% | $10.20 |
| Lunch | 25% | $17.00 |
| Dinner | 40% | $27.20 |
| Incidentals | 20% | $13.60 |
How do companies write travel expense claim rules?
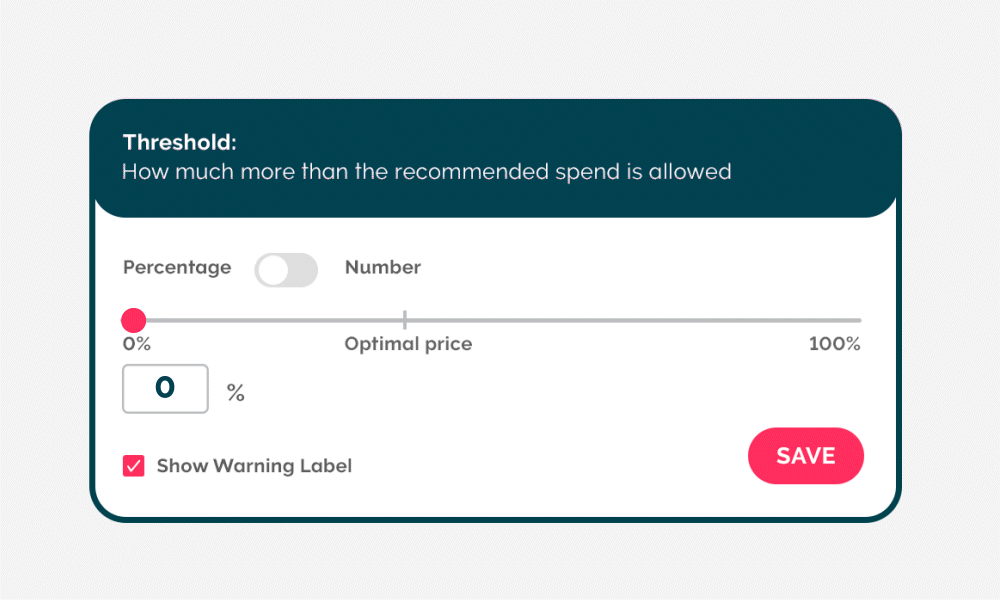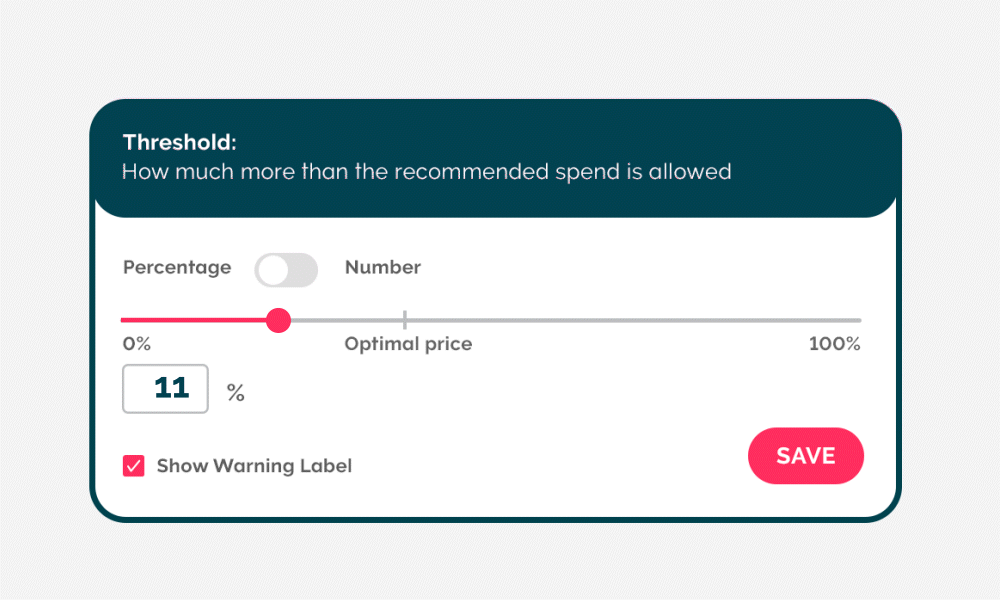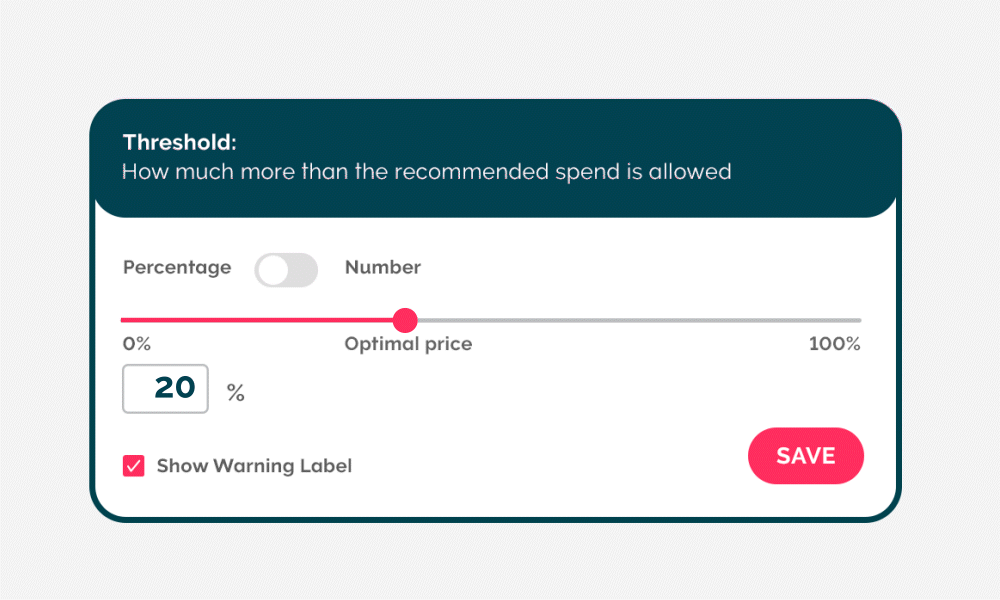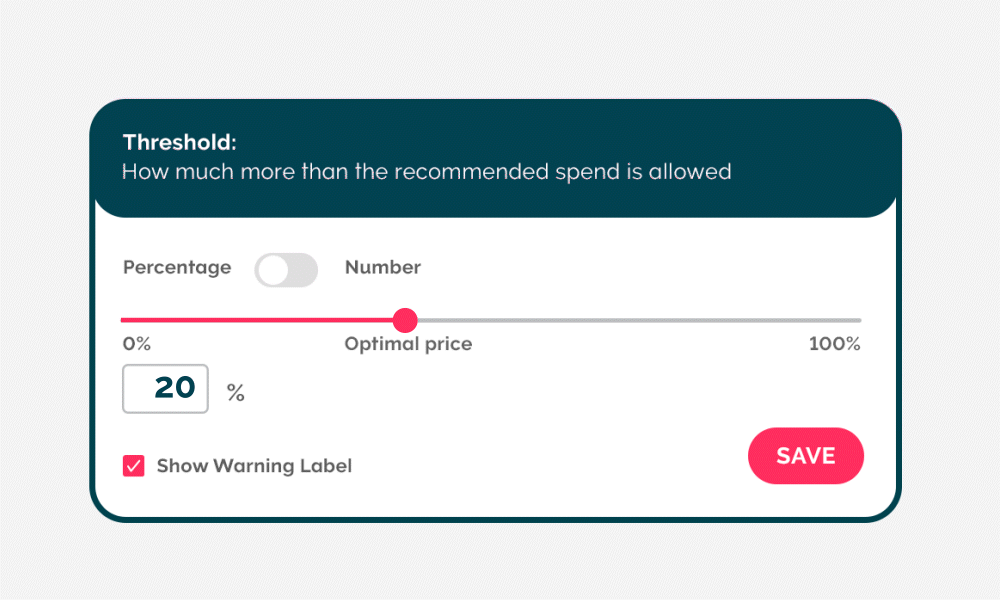
Strong travel expense claim rules name the eligible categories, set a dollar or per diem ceiling for each, require documentation above a set threshold, define the approval workflow, and state the reimbursement timeline in one document, so nothing is left to interpretation after the trip ends.
A travel expense policy fails for one of two reasons: it is too vague to answer real questions, or it is too complicated for travelers to bother following. The fix is the same set of building blocks used by every well-run T&E program, adjusted for company size and travel volume.
Start with the categories and caps above, add the daily allowance method, then layer on the administrative rules that keep everything defensible for tax and audit purposes. Companies that skip the documentation and approval steps tend to see the most overspend, because nothing stops a traveler from booking outside policy until someone spots it weeks later on a credit card statement.
For small and mid-sized businesses especially, the ROI on every trip depends on this. Skip the guardrails, and that ROI leaks out one unapproved upgrade at a time. Building one from a proven travel policy template saves a rewrite from scratch and gives your policy a fighting chance of getting read.
-
1. List every eligible expense category explicitly
Name transportation, lodging, meals, and incidentals individually rather than leaning on a catch-all like "reasonable expenses."
-
2. Set a cap or per diem rate for each category
Anchor lodging and meal caps to GSA or high-low rates so the numbers are defensible, not arbitrary.
-
3. Define the documentation threshold
Most US policies require a receipt for any single expense over $75, consistent with IRS substantiation guidance, and expense integrations like Ramp and Emburse can capture and route that documentation automatically instead of leaving it to a shoebox of receipts.
-
4. Build in an approval workflow
Route anything above a set dollar amount, or any out-of-policy booking, to a manager before it is paid.
-
5. State the submission and reimbursement timeline
A 30-day submission window and a 60-day substantiation ceiling keep the policy inside IRS accountable-plan rules.
-
6. Confirm state-specific reimbursement requirements
California, Illinois, Massachusetts, New York, and several other states legally require reimbursement of necessary business expenses, so multi-state employers need those floors built in.
Are travel reimbursements taxable to employees?
Reimbursements are tax-free under an IRS accountable plan: the expense needs a business connection, the employee must substantiate it within a reasonable period, and any excess advance must be returned. Fail any test and the reimbursement becomes taxable wages.
Get this one wrong, and every reimbursement turns into payroll tax exposure. This is the rule that matters most in the whole policy. An accountable plan has exactly three requirements, no wiggle room. One, a business connection: the trip needs a legitimate purpose. Two, timely substantiation: receipts, dates, amounts, and business purpose, submitted within a reasonable window, which the IRS treats as automatically satisfied inside 60 days. Three, return of excess: any travel advance bigger than what got spent comes back, generally within 120 days.
Nail all three, and the payment isn't wages. No withholding, no FICA, nothing on the W-2. Miss even one, say a flat monthly "travel allowance" with zero expense reporting attached, and the whole payment becomes taxable income on that W-2.
That's also why a documented per diem policy beats an informal one every time: per diem paid at or below the federal rate counts as automatically substantiated, cutting the ambiguity for employee and finance team alike. Automating that substantiation instead of chasing it by hand is exactly what pairing Melon with integrations, like Ramp and Emburse, was built to solve.
What are the benefits of a clear travel expense policy?
A clear policy cuts approval delays, keeps reimbursements tax-free, reduces off-policy spend, and gives finance real-time budget visibility. It also removes the guesswork that frustrates travelers and slows down expense report turnaround for HR and accounting teams alike.
The return on a well-documented policy shows up in three places: money, time, and trust. On money, benchmarked caps and per diem rates stop the slow leak of "reasonable" expenses that creep past budget every quarter. On time, a published set of rules means fewer back-and-forth emails between travelers and accounting over what qualifies.
On trust, travelers who know exactly what they can claim, and see it reimbursed on a predictable timeline, spend less energy worrying about money on a trip that is stressful enough already. Finance and HR teams get an added bonus: audit-readiness. A policy anchored to GSA and IRS benchmarks keeps business travel spend defensible if a reimbursement is ever questioned, because the caps come from the same source an examiner would check.
Getting there is a lot smoother with business travel reporting that shows exactly where the money went, in real time, instead of during a scramble at quarter close.
- Predictable budgeting: Per diem-based caps let finance forecast travel spend without waiting on receipts.
- Faster reimbursement cycles: Pre-approved categories and thresholds cut back-and-forth approvals.
- Tax-safe reimbursements: Alignment with accountable-plan rules keeps payments off employees' W-2s.
- Fewer policy violations: Explicit caps reduce the ambiguity that leads to off-policy bookings.
- Stronger traveler experience: Clear rules reduce the guesswork of expensing a business trip.
- Audit-ready documentation: Rates benchmarked to GSA and IRS standards are easier to defend under review.
Corporate Traveler works exclusively with SMEs to build travel policies around your actual business, not a one-size-fits-all playbook, and to pair that policy with automation through integrations like Ramp so nobody's chasing receipts by hand.
Let's build a travel policy that protects your ROI
Ready to stop overspending? Tell us your headcount plus your current per diem setup, and we'll help you build a policy that keeps finance happy and travelers even happier.
FAQs
-
Can employees claim mileage for driving their own car on a business trip?
Yes. Employees can claim mileage using the IRS standard mileage rate, which increased to 76 cents per mile effective July 1, 2026, up from 72.5 cents earlier in the year, per IRS Announcement 2026-11. This rate covers fuel, maintenance, and depreciation, so no separate receipts are needed for those costs.
-
Do employees need receipts for every expense?
Not always. Per diem-based meal and incidental claims do not require itemized receipts. Actual-cost claims generally do, and IRS guidance treats any single expense over $75 as needing documentation regardless of method.
-
What happens if an employee spends more than the daily allowance?
The excess is typically the employee's responsibility unless a manager pre-approves it. Some companies allow occasional coverages with documented justification, but the per diem rate itself is not renegotiated trip by trip.
-
Is per diem the same in every US city?
No. The GSA sets a standard CONUS rate of $178 a day for FY2026 for most locations, but roughly 300 higher-cost cities and resort areas carry their own, higher published rates that change seasonally in some cases.
-
Can a company pay a flat travel allowance instead of following per diem rules?
It can, but a flat allowance with no expense accounting is treated as a non-accountable plan, which makes the entire payment taxable wages to the employee, unlike a properly structured per diem or actual-cost reimbursement.
-
Are state laws different from federal per diem rules?
Yes, in some states. California, Illinois, Massachusetts, and New York, among others, legally require employers to reimburse employees for necessary business expenses, independent of whatever per diem method the company chooses federally.
Related resources


